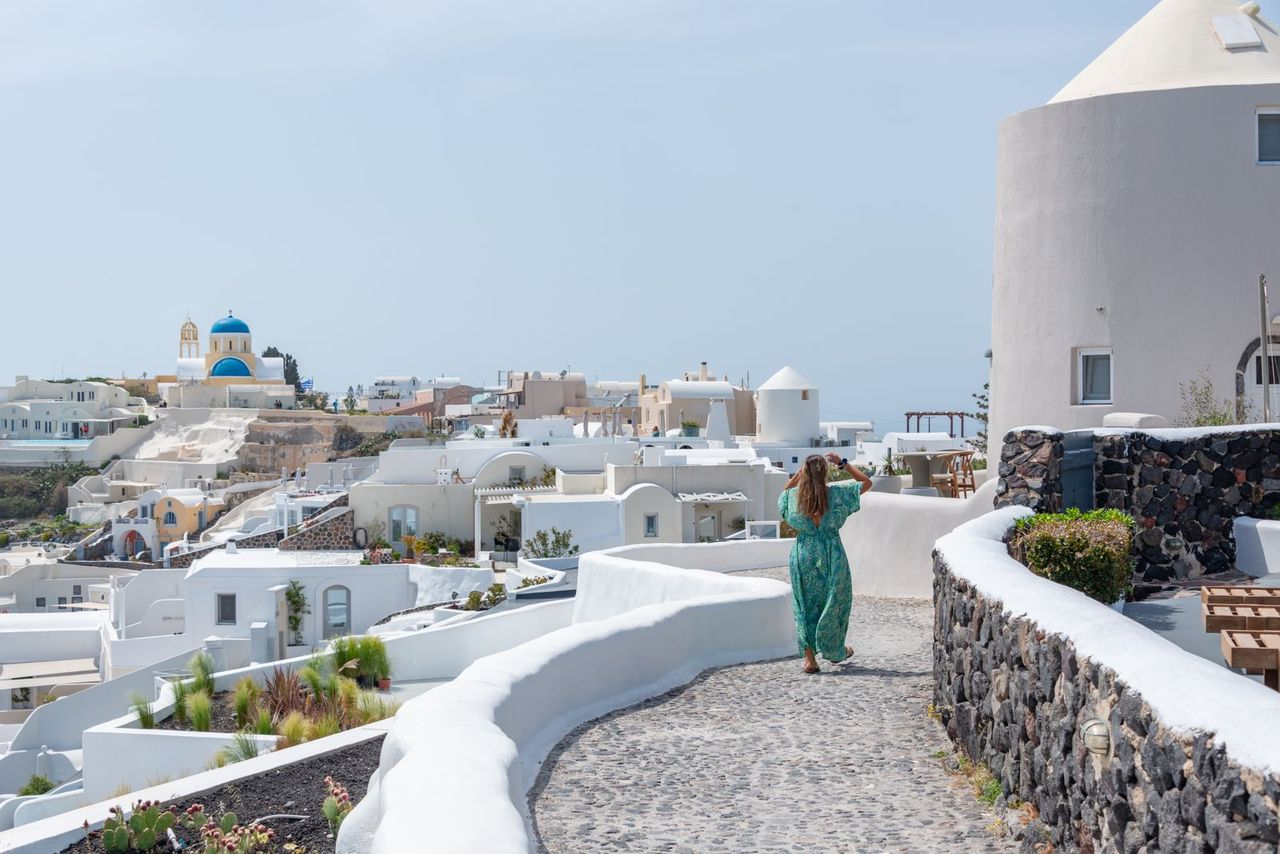
Greece is one of Europe’s most popular travel destinations, ranking consistently among the top ten tourism economies worldwide. The country recorded 35.9 million international arrivals in 2024, its highest-ever figure, alongside €21.7 billion in tourism receipts - a sector that now accounts for roughly 25% of GDP and supports around one in five jobs. Below we’ve compiled the key figures from ELSTAT (the Hellenic Statistical Authority), the Bank of Greece, and INSETE (the Greek Tourism Confederation’s research institute).
International Arrivals
Greece first broke the 30-million barrier in 2019 (31.3 million), then saw arrivals collapse during 2020–2021 before a steep recovery curve that has since pushed numbers beyond pre-pandemic highs.
| Year | International Arrivals | Change YoY |
|---|---|---|
| 2019 | 31.3 million | +3.6% |
| 2020 | 7.4 million | −76.4% |
| 2021 | 14.7 million | +98.6% |
| 2022 | 27.8 million | +89.1% |
| 2023 | 32.7 million | +17.6% |
| 2024 | 35.9 million | +9.8% |
Source: Bank of Greece / ELSTAT Border Survey.
The 2024 figure represents a 14.7% increase on the previous record set in 2019, confirming Greece’s sustained post-pandemic growth rather than a one-off rebound.
Tourism Revenue
Tourism receipts (money spent by visitors inside Greece) have grown at a faster rate than arrivals, reflecting higher average spend per trip driven partly by a shift toward premium accommodation and longer stays.
| Year | Tourism Receipts | Change YoY |
|---|---|---|
| 2019 | €18.2 billion | - |
| 2021 | €10.3 billion | - |
| 2022 | €17.6 billion | +70.9% |
| 2023 | €20.4 billion | +15.9% |
| 2024 | €21.7 billion | +6.4% |
Source: Bank of Greece Balance of Payments statistics.
Average spend per visitor reached approximately €604 in 2024, up from €589 in 2023. Tourists staying in hotels spent an average of €710 per trip versus €430 for those in self-catered or Airbnb-style accommodation.
Top Source Markets
The United Kingdom, Germany, and the United States consistently rank among Greece’s three largest source markets. The US has climbed sharply over the past decade, while France and Poland have both entered the top-ten regularly since 2022.
| Rank | Country | Arrivals (2024, approx.) | Notes |
|---|---|---|---|
| 1 | United Kingdom | 4.2 million | Largest single source market |
| 2 | Germany | 3.6 million | Strong Crete and Rhodes demand |
| 3 | France | 2.4 million | Growing 12% YoY |
| 4 | United States | 2.1 million | Up from 1.1m in 2019 |
| 5 | Italy | 1.9 million | Ionian islands popular |
| 6 | Albania | 1.7 million | Largely land border crossings |
| 7 | Romania | 1.3 million | Budget segment dominant |
| 8 | Netherlands | 1.2 million | High average spend |
| 9 | Poland | 1.1 million | Fast-growing market |
| 10 | Israel | 900,000 | Strong Athens and Crete focus |
Source: INSETE research briefings 2024/2025; Bank of Greece frontier surveys.
US visitors spend considerably more per trip than European counterparts - approximately €1,100–€1,300 on average - making them a high-value segment despite not being the largest by volume.
Most Visited Destinations
Greece’s tourism is heavily island-concentrated. The three island clusters - the Cyclades, Dodecanese, and Ionian - account for the majority of leisure arrivals, while Athens dominates city-break and cultural tourism.
| Destination | Annual Visitors (2024 est.) | Key draw |
|---|---|---|
| Athens | 6.5–7 million | Culture, history, city breaks |
| Santorini | 3.5–4 million | Honeymoon, photography, luxury |
| Crete | 5–5.5 million | Beaches, hiking, family resorts |
| Mykonos | 2.5–3 million | Nightlife, luxury, summer crowds |
| Rhodes | 3–3.5 million | Medieval Old Town, UK charters |
| Corfu | 2–2.5 million | British and Italian leisure travel |
| Thessaloniki | 1.5–2 million | City tourism, gastronomy |
| Zakynthos | 1.5–2 million | Turtles, beaches, youth market |
Santorini and Mykonos have faced overtourism pressure in peak season. Santorini’s Caldera villages are designed for roughly 8,000 day visitors but regularly see 15,000–18,000 in July–August. The regional government now limits cruise ship daily disembarkations to 8,000 passengers (implemented from 2024).
Seasonality
Greece’s tourism is among the most seasonal in Europe. Roughly 65% of annual arrivals fall between June and September, creating infrastructure strain on islands while leaving many properties idle from November through March.
| Period | Share of Annual Arrivals |
|---|---|
| June–September | ~65% |
| April–May | ~15% |
| October | ~8% |
| November–March | ~12% |
The Greek Tourism Ministry has run campaigns since 2022 to promote shoulder-season travel (April–May and October–November), with some success: October 2024 arrivals were up 19% year-on-year, outpacing summer growth rates.
Accommodation and Overnight Stays
Total overnight stays in licensed accommodation reached approximately 145 million in 2024, up from 133 million in 2023.
- Hotels: Account for roughly 58% of licensed bed-nights
- Registered holiday homes and apartments: ~22%
- Short-term rental platforms (Airbnb, Booking.com etc.): Estimated 25–30 million additional nights, largely untracked in official figures
- Registered tourist accommodation units: Around 11,500 hotels plus 32,000+ licensed rental properties across Greece as of 2024
The luxury and 5-star segment has grown disproportionately. Greece added approximately 4,200 new 5-star hotel rooms between 2021 and 2024, driven by demand from US, Middle Eastern, and high-net-worth European visitors.
Aviation and Entry Routes
Greece has 15 international airports, with Athens Eleftherios Venizelos and Heraklion Nikos Kazantzakis handling the highest volumes.
| Airport | International Passengers (2024) |
|---|---|
| Athens (ATH) | 31.2 million |
| Heraklion (HER) | 11.3 million |
| Rhodes (RHO) | 8.6 million |
| Thessaloniki (SKG) | 7.4 million |
| Mykonos (JMK) | 3.8 million |
| Santorini (JTR) | 3.5 million |
Source: Fraport Greece / Hellenic Civil Aviation Authority annual data.
Charter flights remain significant for UK, German, and Scandinavian markets targeting islands. Scheduled low-cost carriers (Ryanair, easyJet, Wizz Air) have expanded rapidly on mainland routes, particularly into Athens and Thessaloniki.
Cruise Tourism
Greece is the leading cruise destination in the Eastern Mediterranean. Piraeus port near Athens handles the most call-overs; Santorini, Mykonos, Rhodes, Corfu, and Katakolon (for Olympia) are the most frequent stops.
- Total cruise passengers (2024): approximately 6.1 million passenger arrivals
- Piraeus: received approximately 720 cruise calls in 2024, making it Europe’s third-busiest cruise port by calls
- Cruise contribution to GDP: estimated €1.4 billion in direct spending (Hellenic Shortsea Shipowners Association)
Cruise day-trippers are counted separately from the 35.9 million overnight arrival figures above.
Economic Impact
Tourism’s contribution to the Greek economy has grown significantly over the past decade, becoming the country’s single most important export sector.
- Share of GDP: Tourism directly and indirectly contributes approximately 24–26% of GDP (Bank of Greece, INSETE 2024)
- Employment: approximately 870,000 jobs directly in tourism and hospitality; 1.2 million including indirect employment (roughly 1 in 4 jobs)
- Tax contribution: VAT on accommodation (13%) and services generated €3.8 billion in 2023
- Tourism trade balance surplus: €15.4 billion in 2024 - tourism single-handedly covers a significant portion of Greece’s goods trade deficit
Outlook for 2026–2027
INSETE’s 2025 forecasts projected continued growth toward 37–38 million arrivals by 2026, with the key constraints being airport capacity at Athens and peak-season crowding on the most popular Cyclades islands. Government policy goals include:
- Extending the tourist season beyond September through tax incentives for autumn bookings
- Increasing average spend through promotion of premium experiences (wine tourism, gastronomy, wellness)
- Dispersing visitors to undervisited mainland regions - Epirus, the Peloponnese, and Central Greece - which together receive under 8% of international overnight stays despite significant cultural heritage
Data sources: Bank of Greece (Balance of Payments, Border Survey), ELSTAT (Hellenic Statistical Authority), INSETE (Greek Tourism Confederation Research Institute), Fraport Greece, Hellenic Civil Aviation Authority. Figures updated October 2026 using 2024 full-year data unless otherwise noted.